
If your roof insurance deductible looks a lot bigger than it used to, the most likely reason is that your policy now uses a percentage deductible for wind and hail instead of a flat dollar amount. In Texas, that percentage is often 1% to 2% of your dwelling coverage, so the deductible rises with the insured value of your home. The exact number is on your declarations page, and it is worth reading before a storm ever hits Round Rock.
Flat deductibles versus percentage deductibles
A flat deductible is a fixed dollar amount. You pay that much toward a covered loss and the insurer pays the rest. A percentage deductible is tied to your dwelling coverage limit, which is the amount it would take to rebuild your house. As home values and rebuild costs in Williamson County have climbed, dwelling limits have climbed with them, and a percentage deductible climbs right alongside.
Many Texas policies carry two deductibles: an all-other-perils deductible for things like fire or a burst pipe, and a separate wind and hail deductible that is usually the larger of the two. Roof damage from a hailstorm falls under the second one. That is the number most Round Rock homeowners are surprised by when they call us after a storm.
Why Texas insurers lean on percentage deductibles
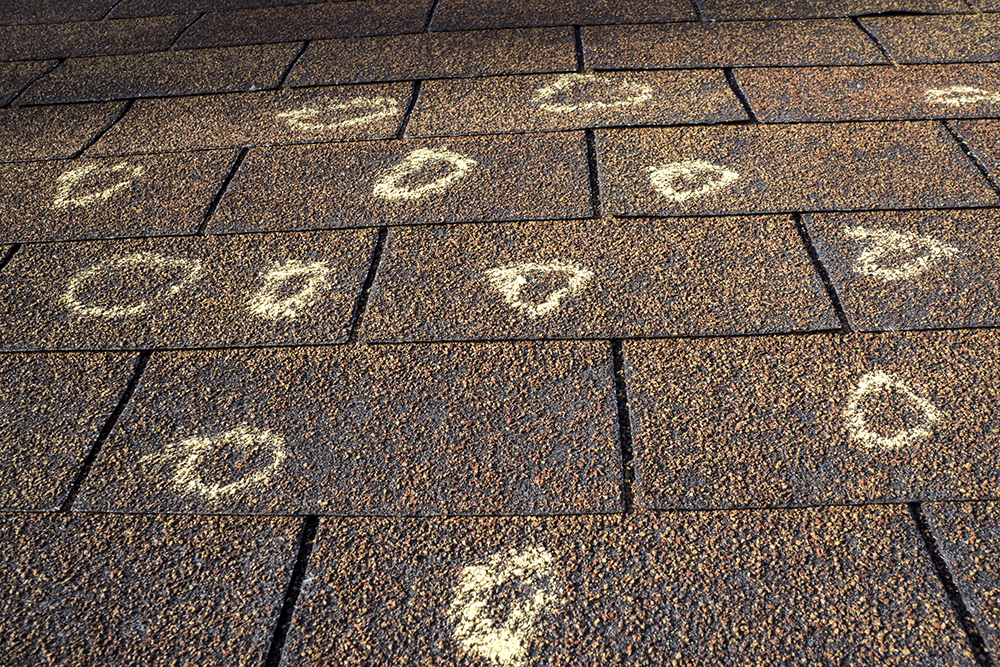
Hail, wind, and summer heat are the main causes of roof damage in Central Texas, and hail season runs roughly March through June with fall storms on top of that. Insurers use higher wind and hail deductibles to keep more of the small-claim cost with the homeowner, which lets them keep premiums lower than they would be with a small flat deductible. You are trading a lower monthly cost for a bigger bill on the day you actually need the coverage.
The trade is not automatically bad. It just means you need to know the number in advance and plan for it, rather than discovering it after an adjuster has already been on your roof.
How to find your real deductible
- Pull your declarations page. It is the summary page at the front of your policy. Look for a line labeled wind and hail, windstorm, or named storm.
- Do the math. If it shows a percentage, multiply it by your dwelling coverage limit, not by your home's market value and not by the total premium.
- Ask your agent to confirm in writing. Deductible structures change at renewal, and a quick email now saves an argument later.
For a plain-English walkthrough of how these deductibles are applied to a roof claim, read What Is a Roof Insurance Deductible?
What a high deductible means for a roof claim
Your deductible comes off the top of whatever the insurer approves. If a storm knocks off a few shingles and the repair costs less than your deductible, filing a claim gets you nothing and still puts a claim on your record. One claim can affect your premiums, so a claim that pays out zero is the worst of both worlds.
That is why we tell every homeowner to get a free professional inspection before calling the insurance company. We document the damage with photos, tell you honestly whether it looks like a repair or a full replacement, and give you a guaranteed price. The quoted price is the price, not an estimate, so you can compare it directly against your deductible and decide whether a claim makes sense. Our full walkthrough is on the insurance process page.
Can a roofer just cover my deductible?
No, and any roofer who offers to is breaking Texas law. Since HB 2102 passed in 2019, a roofing company cannot pay, waive, rebate, or absorb your deductible, and insurers can require proof that you paid it. A contractor who advertises "free roof, we eat the deductible" is asking you to take part in insurance fraud, and the homeowner is the one holding the policy. We cover exactly how that law works in Can a Roofing Company Pay My Deductible in Texas?
What a legitimate Round Rock roofing company can do is help you document the damage thoroughly, meet the adjuster on site, and make sure the scope of work the insurer approves matches what your roof actually needs. That often matters more to your bottom line than the deductible itself.
Ways to manage a high deductible
- Review the percentage at renewal. Some carriers offer a choice of wind and hail deductible levels. A lower percentage usually means a higher premium, so weigh both numbers against how often storms hit your neighborhood.
- Plan for the cash. Treat the deductible like any other emergency expense. Knowing the number lets you set money aside or arrange financing before you need it.
- Ask about financing. KangaRoof offers financing options for homeowners who would rather spread the deductible out. Details are on our financing page.
- Keep the roof maintained. Sealed flashing, clear gutters, and prompt small repairs reduce the odds that a storm turns into a claim in the first place.
What to do next
- Find your declarations page and write down your wind and hail deductible as a dollar figure.
- After any hail or high-wind event, schedule a free inspection before you call your insurer.
- Compare the guaranteed repair or replacement price against your deductible. If the damage is below it, pay out of pocket and keep your claim history clean.
- If the damage clearly exceeds the deductible, file the claim yourself and choose your own roofer. Texas law gives you that right.
- Never sign with a contractor who promises to make your deductible disappear.
KangaRoof has been serving Round Rock, Austin, Georgetown, Pflugerville, Cedar Park, and the surrounding area since Scott Feller founded the company in 1992, and we handle insurance-related roof work every week. If you want a straight answer on whether your damage is worth a claim, call (512) 388-7663 to schedule your free roof inspection.
Related reading
Topics: