Hail Damage Roof Insurance Claims in Texas: Step-by-Step
September 21st, 2026
7 min read
A hail damage roof insurance claim in Texas follows a predictable path: document the storm, get a free professional inspection before you call your insurer, confirm the damage is worth more than your deductible, file the claim, meet the adjuster with your roofer present, review the scope, get the work done, and collect the recoverable depreciation at the end. Most claims that go wrong go wrong at one of those steps, usually because the homeowner filed too early, met the adjuster alone, or accepted the first scope without checking it. This is the step-by-step version for Central Texas homeowners, where hail season runs roughly March through June with fall storms on top, and where Round Rock saw hail again in late summer 2026. If you are still deciding whether to file at all, read Will Insurance Pay for My Roof? first. This guide picks up once you have decided to move forward.
Step 1: Document the storm and the obvious damage
The day of the storm, write down the date and approximate time, and take photos of anything you can see safely from the ground: hail on the lawn or patio next to something for scale, dents in the gutters, downspouts, mailbox, or the top of the AC unit, shingles in the yard, and any leaks or ceiling stains that appear in the next few days. Save any weather alerts or local news reports. You do not need to prove hail size yourself. You just need the timeline. If you are not sure whether your neighborhood was hit, our Central Texas hail history page tracks storm activity across the area.
Step 2: Get a free inspection before you call your insurer
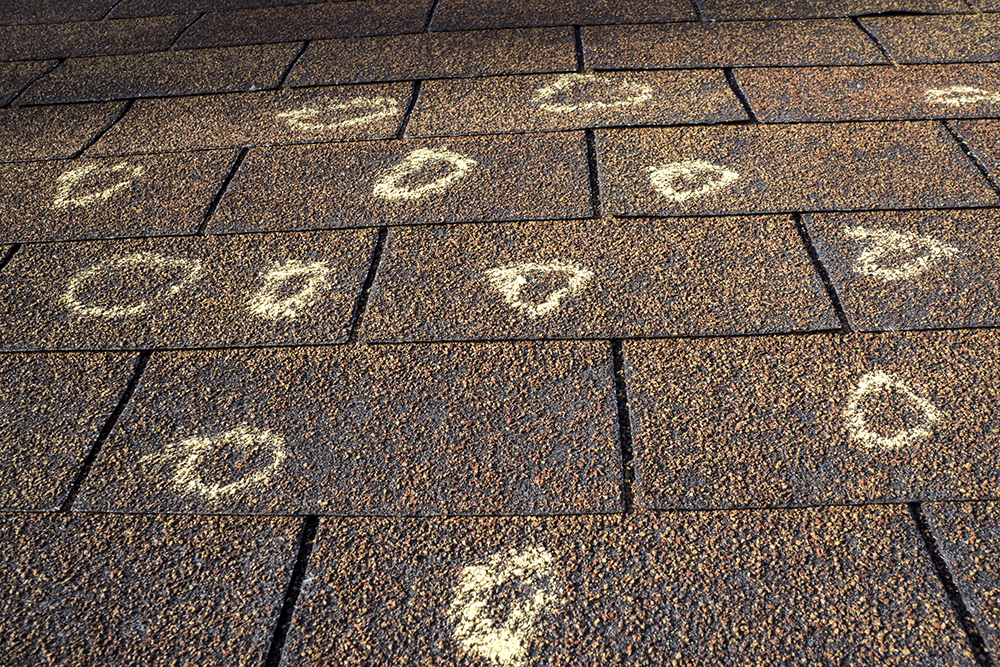
This is the step that protects you. A KangaRoof storm inspection is free, in person, and produces the documentation an adjuster expects: test squares on each slope with hail hit counts, photos of every bruise and every dented soft metal, and a written summary. It tells you three things before you commit to anything:
- Whether the damage is actually hail and wind, or age and wear that no policy covers.
- How widespread it is, which is what determines repair versus replacement.
- Roughly what the repair would cost, so you can compare it with your deductible.
Filing first and inspecting later flips that order, and a claim filed for damage that turns out to be minor or non-storm-related goes on your claims history whether or not it pays anything. Our storm and hail damage page explains what we look for, and this guide to roof hail damage shows what bruising looks like up close.
Step 3: Decide whether the damage exceeds your deductible
Texas homeowners policies commonly carry percentage deductibles tied to the home's insured value, and on many Central Texas homes that works out to several thousand dollars. If the inspection shows a repair that costs less than your deductible, filing gains you nothing. If it shows slope-wide bruising that calls for a full replacement, the claim is almost certainly worth pursuing. It is a simple math decision once the inspection gives you a real number.
Step 4: File the claim
In Texas, the homeowner files the claim, not the roofer. Call the claims number on your policy or use your insurer's app, give the storm date, describe the damage briefly and factually (hail damage to the roof, dented gutters, whatever the inspection found), and ask for the claim number and the adjuster assignment. You do not need to speculate about cost or argue for replacement on this call. Keep it short and accurate. Write down the claim number, the adjuster's name and phone number, and the date you filed. Every later conversation will reference that number.
Step 5: Meet the adjuster with your roofer present
The insurer will send an adjuster to inspect the roof. Schedule that visit for a time your roofer can be there too. This is the most important appointment in the whole process, and it is one you should never take alone. The adjuster walks the roof, marks test squares, counts hits, and decides what the insurer will pay for. A roofer who has already inspected the roof can point out every slope with damage, make sure the hit counts match, flag collateral damage on vents and gutters, and note items like decking, drip edge, and ventilation that are easy to leave out of a scope. After a big storm adjusters are working through many roofs, and a second set of trained eyes keeps things from getting missed. Texas law lets you choose your own roofer; you are never required to use one your insurer suggests.
Step 6: Review the scope and handle supplements
After the visit, the insurer issues a scope of loss: an itemized list of what they will pay for, line by line, with quantities and unit prices. Read it against the inspection report. Common gaps include missing slopes, undercounted squares, no line for starter or ridge cap, no decking replacement, no permit fees, and no ice and water shield or drip edge where code requires it. When the scope is short, your roofer submits a supplement: a documented request for the insurer to add the missing items. Supplements are a normal part of the process, not a fight, and a good roofer handles the paperwork. We explain how they work in What Is a Supplement?
Step 7: Understand ACV, RCV and depreciation
Your policy pays on one of two bases, and the difference decides how much money you actually receive.
- Replacement cost value (RCV). The insurer agrees to pay what it costs to replace the roof with like materials today. They typically pay in two parts: an initial check for the actual cash value, then the held-back depreciation after the work is complete.
- Actual cash value (ACV). The replacement cost minus depreciation for the roof's age and condition. On an older roof, the depreciation can be a large share of the total, and on an ACV policy that share is never paid.
Depreciation is the insurer's estimate of how much of the roof's useful life was already used up. On an RCV policy it is recoverable: once the roof is installed and the final invoice is submitted, the insurer releases it. On an ACV policy it is not. Check your declarations page for which you have, and if your roof is older, ask your agent whether your policy has an ACV roof schedule, which some Texas policies now include. This is general information; your own policy language controls.
Step 8: Pay your deductible, and only your deductible
The deductible is your share of the claim, and in Texas it is required. Under HB 2102 (2019), a roofing contractor cannot legally waive, absorb, rebate, or otherwise pay your deductible, and offering to do so is a crime for the contractor. If a roofer knocks on your door after a storm and says the roof will cost you nothing, that is the sign to close the door. A contractor willing to commit insurance fraud on your behalf is not one you want on your roof. We cover the law and the reasons behind it in Can a Roofing Company Pay My Deductible in Texas? Your out-of-pocket cost on an approved RCV claim is normally the deductible plus any upgrades you choose, such as moving to a Class 4 impact-resistant shingle.
Step 9: Get the work done and release the depreciation
Once the scope and supplements are settled, the roofer schedules the replacement. At KangaRoof the quoted price is the price, not an estimate, and our crews handle everything from tear-off to cleanup. When the job is complete, the roofer sends the final invoice and completion photos to the insurer, and on an RCV policy that triggers the release of the recoverable depreciation. Keep every document: the scope, the supplements, the invoice, the warranty registration, and your own photos. Our insurance process page lays out how we manage each of these hand-offs.
If the claim is denied or underpaid
Denials happen, and they are not always final. Common reasons include an adjuster who found too few hits per test square, damage classified as wear or mechanical rather than hail, a missed filing deadline, or a policy exclusion. Your options usually include requesting a re-inspection with your roofer present, submitting additional documentation, asking for a different adjuster, or invoking the appraisal clause in your policy. Do not accept a denial without reading the reason. Our guide to what to do when a roof claim is denied in Texas walks through each option.
Timelines in general terms
Every policy has a deadline for reporting a claim, often measured in months to a couple of years from the date of loss, so check yours and file well inside it. Adjuster visits after a large regional hail event can take longer to schedule because thousands of homes are affected at once. Supplements add time while the insurer reviews them. Texas insurers also have statutory deadlines for acknowledging, investigating, and paying claims once they have what they need. The practical takeaway: inspect quickly, file promptly, respond to every request from the adjuster the same week, and keep the roofer and the insurer talking to each other.
Mistakes to avoid
- Filing before you know what the damage is or whether it exceeds your deductible.
- Signing an assignment of benefits or a contingency agreement with a door-to-door roofer before your own inspection.
- Meeting the adjuster without your roofer.
- Accepting the first scope without comparing it to the inspection report.
- Letting a contractor "cover" your deductible.
- Waiting months after a storm, then trying to prove the damage was from that storm.
- Making permanent repairs before the adjuster has seen the roof. Temporary tarping to stop active leaks is fine and expected; just photograph the damage first.
FAQ
Should I call my insurance company or a roofer first after hail?
Call a roofer for a free inspection first. It tells you whether the damage is storm-related, how widespread it is, and whether it exceeds your deductible, so you file only when the claim is worth filing.
Does a hail claim cover a full roof replacement?
Only if the damage justifies it. Adjusters evaluate each slope, and a claim can be approved as a repair to one or two slopes rather than a whole roof. Widespread bruising across most slopes is what typically supports full replacement.
What is the difference between ACV and RCV on a roof claim?
RCV pays the full replacement cost, with depreciation held back until the work is done and then released. ACV pays replacement cost minus depreciation for age and condition, and that depreciation is never paid. Your declarations page shows which applies to your roof.
Can my roofer pay my deductible in Texas?
No. Under Texas HB 2102, a contractor cannot waive, pay, or rebate your deductible in any form. You pay the deductible, and any roofer who offers otherwise should be avoided.
What if my hail claim is denied?
Read the denial reason, then request a re-inspection with your roofer present, submit additional documentation, or invoke your policy's appraisal clause. Many denials are reversed once the damage is properly documented.
If hail has hit your neighborhood, call KangaRoof at (512) 388-7663 for a free inspection with photos and full claim documentation before you make a single call to your insurer.
Related reading
Topics: